Merchant Services: The Seasonal Risk You’re Not Managing
Last Updated on September 1, 2026 by Dimitri Akhrin
Why your processor relationship becomes a liability during peak season — and how account oversight prevents surprise holds
Learn why treating your payment processor as set-it-and-forget-it infrastructure leaves you exposed during seasonal spikes. This piece reveals how chargeback surges, reserve holds, and deposit delays catch merchants off guard when dedicated account management is missing.
TL;DR
- Your processor is a seasonal risk variable – During volume spikes, automated risk systems can freeze deposits, impose reserves, and delay funding without warning unless a dedicated account manager pre-clears your thresholds.
- Chargebacks hit after peak season, not during it – Post-peak dispute surges (up 53% in recent quarters) carry $128+ per incident in combined costs and can trigger card network monitoring programs with steep monthly fines.
- Cash flow timing is the hidden cost – A 2 to 3 day deposit delay during peak season creates five-figure gaps between revenue earned and cash accessible, forcing unnecessary borrowing or throttled ad spend at the worst possible moment.
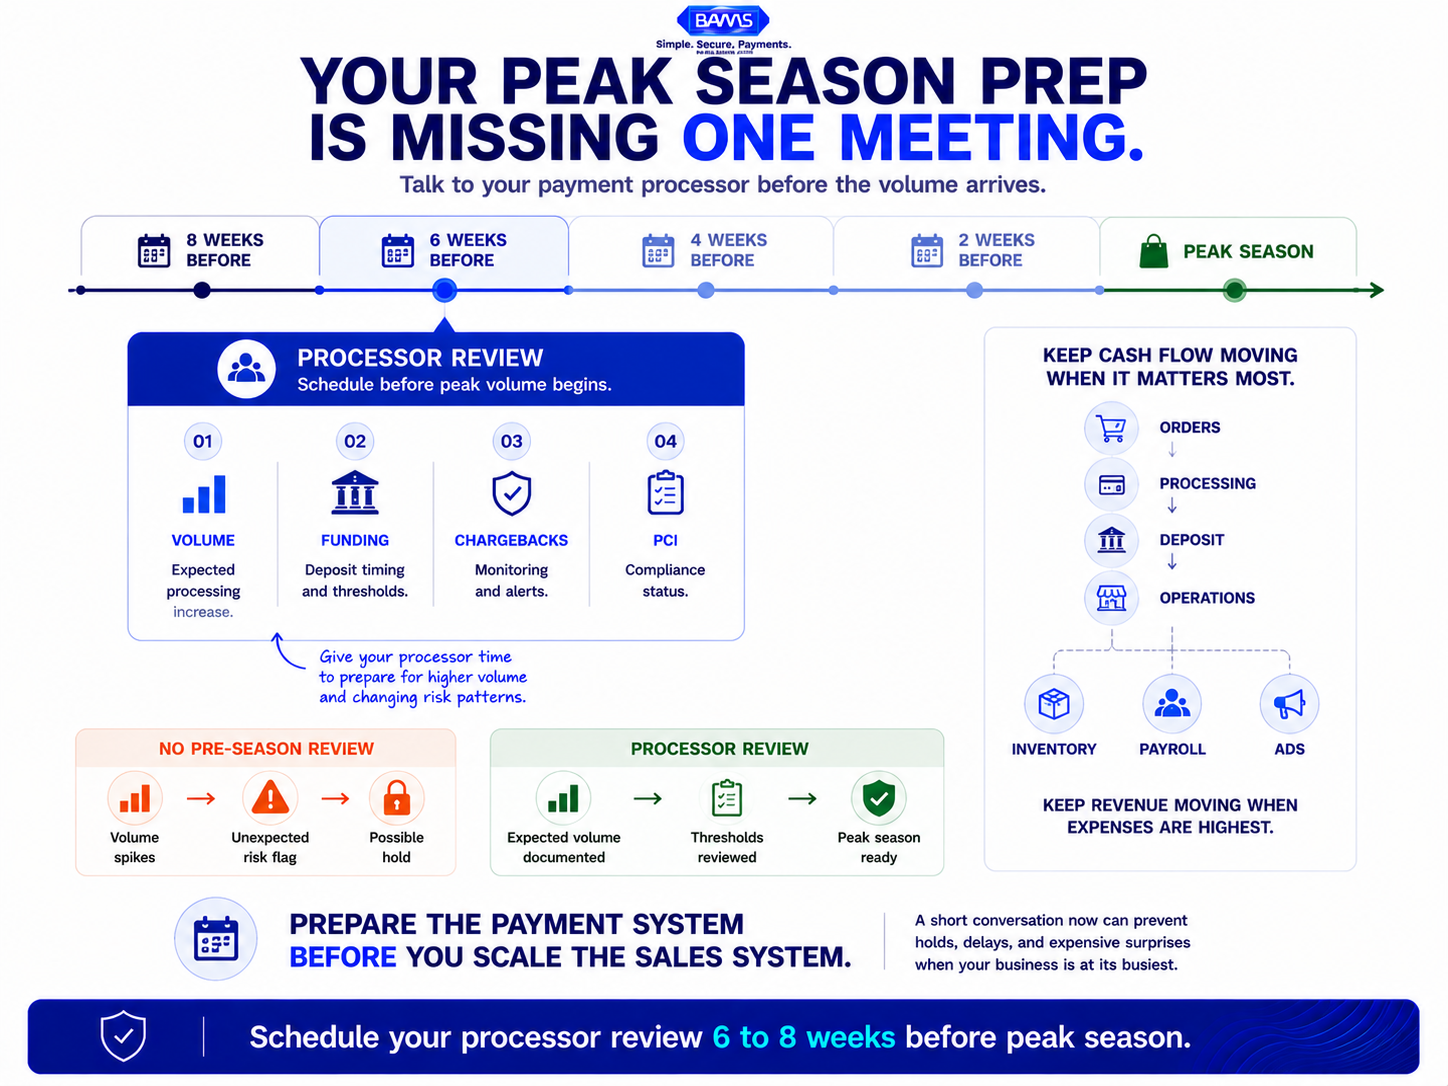
- Pre-season processor review is the most overlooked preparation step – Scheduling a review 6 to 8 weeks before peak season to address PCI compliance, volume thresholds, and chargeback monitoring prevents the costliest surprises.
The Fee You Didn’t Budget For Already Hit Your Account
Every eCommerce manager knows the math changes during peak season. Volume goes up, revenue climbs, and somewhere between the orders and the celebrations, payment processing costs quietly eat into margins you thought were locked. But the real damage isn’t the per-transaction fee you negotiated last January. It’s the chargeback hold your processor placed without warning, the reserve requirement that appeared in your merchant statement like a line item from nowhere, and the deposit delay that landed on the exact day payroll was due.
The “Set It and Forget It” Myth in Merchant Services
Most eCommerce businesses treat their payment processor the way they treat their internet provider. Sign the contract, confirm the rate, and move on. It’s understandable. When you’re running a team of 10 to 50 people, payments feel like plumbing. They should just work.
And for most of the year, they do. Transaction volumes stay predictable. Chargeback ratios stay low. Your effective rate holds steady. The processor sits quietly in the background, and nobody thinks twice about it.
This approach made sense when eCommerce growth was linear and fraud patterns were stable. But seasonal spikes don’t just increase revenue. They increase risk signals. And your processor’s risk team doesn’t distinguish between “healthy growth” and “suspicious activity” unless someone on their side is paying attention to your account specifically.
Your Processor Is a Seasonal Risk Variable, Not a Utility
Here’s what we believe: the relationship between a merchant and their payment processor is the single most underestimated variable in seasonal cost management. Not your ad spend. Not your inventory planning. Your processor.
Because your processor holds the keys to your cash flow. And during peak season, they can turn those keys without calling you first.
What Actually Happens When Volume Spikes
A seasonal sales surge is good news for your business, but an unexpected change in processing volume can look very different to an automated risk system.
Let’s walk through the chain of events that catches growing eCommerce brands off guard every peak season.
Your transaction volume doubles or triples over a 4 to 6 week window. For you, that’s success. For your processor’s automated risk system, that’s a flag. Sudden volume increases trigger fraud detection algorithms designed to protect card networks from exposure. If your processor doesn’t have a human reviewing your account, the system responds mechanically: holds on deposits, rolling reserves, or outright funding delays.
Now layer in the chargeback surge that follows every peak period. Mastercard reports that merchants pay an average of $82 in internal costs and $46 in third-party fees per chargeback, excluding the value of lost goods. That’s $128 per dispute before you even count the product you shipped and won’t get back.
And the timing is brutal. Chargebacks from holiday purchases don’t arrive in December. They arrive in January and February, right when cash flow tightens and Q1 budgets are already stretched. Visa notes that friendly fraud has surged in recent years and accounts for a significant portion of payment disputes.
If your processor sees this spike coming (and they do, because they have the data), the question is simple: are they set up to warn you, or are they set up to protect themselves?
Processors without dedicated account management default to self-protection. Automated holds. Reserve increases. Delayed funding. You find out when you check your bank balance and the deposit isn’t there.
Processors with dedicated account management do something different. They call you before peak season, they review your projected volumes, they pre-authorize higher processing thresholds so the risk system doesn’t flag your growth as suspicious and they monitor your chargeback ratio in real time and alert you before you cross the card network threshold that triggers penalties.
This is the difference between a processor that functions as a utility and one that functions as a partner. And during seasonal volume swings, that difference shows up directly in your payment processing costs.
The Cash Flow Timing Problem Nobody Talks About
There’s a specific cash flow problem that almost no one in the payments industry addresses publicly. During peak season, your expenses (inventory, shipping, ad spend, temporary staff) spike immediately. But if your processor holds deposits for 2 to 3 business days, or places a rolling reserve on your account, your revenue arrives late.
You’re funding peak operations out of pocket while your processor sits on your money. For a business processing $500K during a holiday window, even a 48-hour delay can create a five-figure gap between what you’ve earned and what you can access. That gap forces borrowing, delays vendor payments, or worse, forces you to throttle marketing spend at the exact moment when every dollar of ad spend generates the highest return.
This is where next-day funding becomes a strategic lever, not a convenience. BAMS offers next-day funding alongside proactive account management specifically to prevent this seasonal cash flow crunch. When your processor deposits revenue the next business day and pre-clears your volume thresholds before peak season, you’re not scrambling to cover the gap between orders and cash.
If This Is Right, Your Pre-Season Checklist Is Missing the Most Important Item
Inventory and advertising are not the only systems that need preparation. Reviewing payment operations 6 to 8 weeks before peak season gives your processor time to prepare for higher volume and changing risk patterns.
Most eCommerce teams prepare for peak season by stress-testing their site, scaling ad budgets, and stocking inventory. Almost none of them schedule a pre-season review with their payment processor. If the argument above holds, that’s the most expensive oversight on the list.
Consider what’s at stake. A PCI compliance review that’s overdue could mean your transactions are downgraded to higher interchange categories, silently inflating your effective rate during the highest-volume weeks of the year. Hidden fees like interchange downgrades and batch fee stacking compound when volume scales. And a chargeback ratio that creeps past card network thresholds during the post-peak dispute window can trigger monitoring programs with monthly fines of $10,000 or more.
Every one of these risks is visible to your processor before it becomes visible to you. The question is whether anyone at your processor is looking.
Stop Thinking “Payment Processor.” Start Thinking “Seasonal Risk Partner.”
The reframe is simple. Your payment processor isn’t a pipe that moves money from customer to bank account. It’s a risk partner that either absorbs seasonal volatility on your behalf or passes it through to you as fees, holds, and delays.
When you evaluate your processor through this lens, the criteria shift entirely. Rate matters, but it’s table stakes. What matters more: Do they assign a dedicated account manager who knows your business? Will they pre-authorize volume increases before peak season? Do they offer next-day funding that keeps cash flow intact when expenses spike? Do they monitor your chargeback ratio proactively and alert you before it triggers penalties?
The best merchant services relationships aren’t the cheapest ones. They’re the ones where your processor sees the storm coming and calls you before it hits.
Your Processor Already Has the Data. The Only Question Is What They Do With It.
U.S. banks collected nearly $66 billion in interchange fees in 2025, up from $64 billion in 2024 and $52 billion in 2021. The merchants who control their share of that cost won’t be the ones who negotiated the lowest basis points. They’ll be the ones whose processor picked up the phone in October and said, “Here’s what we see coming. Let’s get ahead of it.”
That call is worth more than any rate reduction. And if your processor never makes it, that tells you everything you need to know.
Frequently Asked Questions
When should businesses review their payment processing setup before peak seasons?
At least 6 to 8 weeks before your projected volume increase. This gives your processor time to pre-authorize higher thresholds, confirm your PCI compliance review is current, and adjust risk settings so automated holds don’t freeze your deposits mid-surge.
Why do payment processing costs spike beyond just higher transaction volume?
Volume increases trigger risk flags that lead to deposit holds, rolling reserves, and interchange downgrades. Post-peak chargebacks add per-incident fees ($15 to $25 from card networks alone) plus internal labor costs, compounding the damage well after the season ends.
How can a dedicated account manager reduce seasonal processing costs?
A dedicated account manager monitors your chargeback ratio in real time, pre-clears volume thresholds to prevent automated holds, and flags effective rate drift before it compounds. They turn your processor from a reactive utility into a proactive risk partner.