Reconciliation Best Practices: Why Automation Alone Fails
Last Updated on August 26, 2026 by Dimitri Akhrin
Automated reconciliation won’t fix what you don’t understand — start with a daily manual habit first
Learn why jumping straight to automated reconciliation tools creates faster confusion, not clarity. This piece makes the case for a daily manual check as the foundation of real exception management.
TL;DR
- Your dashboard and bank won’t match by design – Processor fees, chargebacks, refunds, and settlement timing create a legitimate gap between gross sales and net deposits.
- Automation without understanding makes errors faster – 5 to 10% of reconciliations require human judgment; you need to recognize patterns before software can flag exceptions effectively.
- Build a daily manual habit first – Spend 15 minutes each morning for 30 days comparing gross sales to deposits, and you’ll develop the instinct that makes any tool actually useful.
- Treat reconciliation as cash flow radar, not bookkeeping – Daily checks tell you how fast money moves, what’s being deducted, and whether your processor is performing as promised, giving you confidence to reinvest.
Your Dashboard Says One Thing. Your Bank Says Another.
You sold $14,000 yesterday. Your payment dashboard confirms it. But your bank account shows $11,200. The difference isn’t theft. It’s not even an error, technically. It’s the gap between what you earned and what actually arrived, and it’s the single most common source of cash flow anxiety in eCommerce. Reconciliation best practices exist for a reason, but most operators skip straight to software before understanding the problem they’re solving.
The Automation Reflex
The standard advice is straightforward: automate your reconciliation. Match transactions to deposits with software. Eliminate the spreadsheet. And to be fair, this advice became popular because it works at scale. Enterprise finance teams processing thousands of line items per day genuinely need rules-based matching and automated exception management.
But somewhere along the way, that enterprise logic trickled down to operators running 200 orders a day, and the message became: “Just plug in a tool and stop worrying about it.” The problem is that most eCommerce managers aren’t drowning in volume. They’re drowning in confusion. They don’t need faster matching. They need to understand why the numbers diverge in the first place.
Speed Without Understanding Is Just Faster Confusion
Here’s what we actually believe: automated reconciliation without a daily manual habit is like spell-check without knowing grammar. It catches surface errors and silently lets structural ones through.
Before you automate anything, you need to know what “right” looks like by hand.
Payment reconciliation graphic showing why merchants should understand normal deposits, fees, refunds, and chargebacks before automating reconciliation.
Where the Real Reconciliation Gap Lives
Let’s walk through what actually creates the mismatch between your dashboard and your bank, because it’s rarely one thing.
Your payment dashboard shows gross sales. Your bank receives net deposits. Between those two numbers sits a stack of deductions: processing fees, chargebacks, refund clawbacks, reserve holds, and settlement timing delays. Each one is legitimate. None of them are obvious unless you’re looking.
Consider a typical day. You process $14,000 in sales. Your processor takes its fee (say 2.6% + $0.10 per transaction across 180 orders). That’s roughly $382. Two customers disputed charges from last week, pulling another $150. A refund you issued Tuesday finally settled today, deducting $68. And because today is Monday, your Friday and Saturday deposits are batched together with slightly different timing than you expected.
Your bank shows $11,200 not because something went wrong, but because five different things happened correctly and nobody explained the math.
This is where daily reconciliation earns its keep. Not as an accounting exercise, but as a diagnostic habit. When you manually compare your dashboard totals against your deposit each morning, you start to internalize the rhythm: fees, timing, chargebacks, refunds. Within two weeks, you can eyeball a deposit and know whether it’s in range or something needs investigation.
That human review matters because merchant processing involves multiple steps between the original transaction and the funds ultimately reaching the merchant. The Office of the Comptroller of the Currency’s Merchant Processing handbook describes merchant processing as a system involving authorization, settlement, chargebacks, and other operational and financial risks. Automation can help organize those moving parts, but operators still need to understand how transactions move through the payment process so they can recognize when something does not look right.
The exceptions matter because even a relatively small discrepancy can affect your understanding of available cash. Processing costs are one part of that equation. Federal Reserve data tracks interchange fees and transaction values across covered debit card issuers, illustrating that payment costs are a measurable component of the transaction flow. For merchants, reconciling those costs alongside refunds, chargebacks, and settlement timing helps explain why gross sales and actual bank deposits do not always match.
The operators who catch discrepancies fastest aren’t the ones with the best software. They’re the ones who spent a month doing it by hand and built the instinct to notice when a deposit feels light. They know their average fee load, they know their typical chargeback cadence and they know that a holiday weekend shifts settlement by a day. That pattern recognition is the foundation that makes automation actually useful.
Exception Management Is a Human-First Discipline
Exception management sounds like a system feature. It’s not. It’s a habit. The system can flag the mismatch. But deciding whether a $200 discrepancy is a timing variance (wait a day), a duplicate refund (investigate now), or a fee increase you weren’t notified about (call your processor) requires judgment that no matching rule can replicate.
This is where your processor relationship becomes a reconciliation tool in itself. If your merchant services partner buries fee structures in dense statements and batches deposits unpredictably, every reconciliation becomes a forensic project. BAMS addresses this directly with next-day funding and transparent pricing, which means your deposits arrive on a predictable schedule with fees you can actually trace. That alone eliminates a significant category of timing variances and fee mysteries that make daily reconciliation painful.
If you’re already dealing with chargebacks complicating your reconciliation, building transparency into your checkout flow reduces dispute volume before it ever hits your deposit statement.
If This Is Right, You’re Investing Backwards
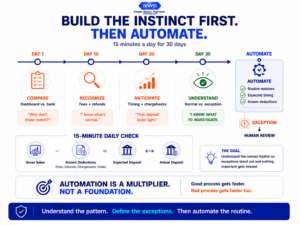
Thirty days of manual reconciliation can teach you the normal rhythm of fees, refunds, chargebacks, and settlement timing before those patterns are handed over to software.
If our thesis holds, then most eCommerce managers are spending money on reconciliation tools before they’ve built the $0 habit that makes those tools effective. They’re automating a process they don’t yet understand, which means they’re trusting software to catch problems they couldn’t identify themselves.
The implication is uncomfortable: you might need to slow down before you speed up. Spend 15 minutes each morning for 30 days comparing your gross sales, known deductions, and net deposit. Build a simple spreadsheet. Track your processor fees as a percentage. Log chargebacks and refunds. Note settlement timing patterns around weekends and holidays.
Then, when you do automate, you’ll know exactly what the tool should be catching. You’ll configure better matching rules. You’ll set smarter exception thresholds. And you’ll notice immediately when something drifts, because you’ve already calibrated your expectations against reality.
Reconciliation Isn’t Accounting. It’s Cash Flow Radar.
Here’s the reframe: stop thinking of reconciliation as a bookkeeping task you do for your accountant. Think of it as cash flow radar. Every daily check tells you how fast your money is moving, what’s being deducted, and whether your processor is performing as promised. That visibility also supports better forecasting: NetSuite explains that cash flow forecasting helps businesses estimate future cash positions by analyzing expected inflows and outflows. Reconciliation strengthens that process by giving you a clearer picture of when payment revenue actually reaches your bank account.
That radar is what lets you confidently reinvest in inventory, increase ad spend on a strong week, or catch a fee creep before it compounds over a quarter. The operators who treat reconciliation as strategic (not administrative) are the ones who can move faster, because they always know where their cash actually is.
Reconciliation best practices don’t start with software. They start with sight.
The Tool Comes After the Instinct
Automation is a multiplier, not a foundation. It makes good habits faster and bad habits more expensive. If you can’t explain why your bank balance is $2,800 short of your dashboard total, no platform in the world will fix that for you. It will just make the mystery move at machine speed.
Build the instinct first. The tools will be waiting.
Frequently Asked Questions
What is deposit reconciliation in merchant services?
Deposit reconciliation is the process of matching your gross sales (what your dashboard shows) against your net bank deposits after accounting for processor fees, chargebacks, refunds, and settlement timing. It confirms that the money you earned actually arrived, minus legitimate deductions.
When should I perform deposit reconciliation for my merchant account?
Daily, ideally each morning. A 15-minute manual check builds pattern recognition around fees, timing, and deductions, which is the foundation for effective automated reconciliation later.
Which factors can affect the timing of merchant service deposits?
Weekends, bank holidays, processor batch schedules, chargeback settlements, and refund processing windows all create timing variances. Choosing a processor with next-day funding eliminates most timing unpredictability.
Sources
- https://www.occ.treas.gov/publications-and-resources/publications/comptrollers-handbook/files/merchant-processing/pub-ch-merchant-processing.pdf
- https://www.federalreserve.gov/paymentsystems/regii-average-interchange-fee.htm
- https://www.netsuite.com/portal/resource/articles/accounting/cash-flow-forecasting.shtml#