Mistakes to Avoid When Choosing a Payment Processor
Last Updated on September 4, 2026 by Dimitri Akhrin
Choosing a Payment Processor Takes More Than Comparing Rates
When margins are tight, it becomes more important than ever for merchants to squeeze as much value as possible from their operations, including payment processing.
The original version of this article was written in the wake of the COVID-19 pandemic, when widespread closures and changes in consumer spending put enormous pressure on businesses. That specific moment has passed, but the underlying issue has not.
Processing costs, cash flow and reliable payment infrastructure still have a direct effect on profitability.
Merchants looking for a new payment processing partner should therefore look beyond a single advertised rate. Pricing structure, support, funding speed, technology compatibility and account terms can all affect what the relationship actually costs once the business starts processing.
The following are three common mistakes merchants make when searching for a payment processor and what to look for instead.

Pricing matters, but merchants should also compare support and funding before choosing a payment processor.
TL;DR
- Do not choose a payment processor based on one advertised rate – Compare the total effective cost, including processor markup, transaction fees, monthly charges, gateway costs, PCI-related fees, chargeback fees and any funding costs.
- Understand how the pricing model works before signing – Interchange-plus pricing separates underlying interchange from processor markup while bundled or tiered pricing can make individual cost components less visible.
- Support becomes important when something goes wrong – Before switching providers, confirm who handles funding questions, terminal or gateway problems, PCI compliance, disputes and unexpected statement charges.
- Funding speed can directly affect cash flow – Ask about the standard settlement schedule and batch cutoff before opening the account. Qualifying BAMS merchants can currently submit eligible transactions before 9 PM ET and receive funds by approximately 7 AM the following business day.
- Compare the complete payment relationship – Pricing, support and funding should be evaluated together because a lower rate may not be worthwhile if deposits are slow, support is difficult to reach or additional fees increase the overall cost.
1) Accepting Unnecessarily High or Unclear Fees
Being in business is all about making money, yet merchants can quietly undercut profitability when they do not understand how their processing fees are structured.
The difference between two providers may look like a fraction of a percentage point. Across hundreds of thousands or millions of dollars in annual card volume, those fractions can become meaningful.
The mistake is not simply choosing a particular type of provider. It is choosing one without understanding the total effective cost.
Payment Service Providers Are Not Automatically the Wrong Choice
The original version of this article described choosing a third-party payment processor such as PayPal as one of the biggest mistakes a merchant could make.
That is too broad in 2026.
Payment service providers can be practical for newer businesses or merchants that value simple onboarding and bundled payment tools. Visa notes that providers such as PayPal, Stripe and Square can combine merchant services, gateway functionality, fraud tools and reporting into one platform.
The tradeoff is that merchants generally have less control over account structure and pricing.
Traditional merchant accounts can offer greater customization and may become more economical as transaction volume increases.
The right choice depends on the business.
Understand the Pricing Model
Merchant accounts can also use very different pricing structures.
With a bundled or tiered model, several types of transactions may be grouped into broader pricing categories.
With interchange-plus pricing, the underlying interchange cost is separated from the processor markup. That can make it easier for the merchant to see where processing costs originate.
BAMS currently offers transparent merchant account pricing, including interchange-plus and volume-based pricing for businesses with larger or more complex processing needs.
The important question is not simply, “What rate are you offering?”
Ask:
- What processor markup applies?
- Are there per-transaction charges?
- What monthly fees apply?
- Are gateway charges separate?
- Are there PCI-related fees?
- What does a chargeback cost?
- Are there minimum-volume requirements?
- Are funding upgrades subject to additional fees?
Then compare the entire monthly cost.
Calculate Your Effective Processing Rate
A merchant statement makes this relatively straightforward.
Total processing costs ÷ total card volume × 100 = effective processing rate
That percentage is much more useful than comparing one advertised transaction rate against another.
It also gives established merchants a baseline for evaluating a new processor.
2) Undervaluing Support
Money may be priority one, but it isn’t everything.
Payment processing sits directly between the customer and the merchant’s revenue. When something goes wrong, the quality of the support relationship can become more important than a small difference in transaction pricing.
Shopping for a processor on price alone without considering service and support is therefore a mistake.
Before switching providers, find out what support actually looks like.
- Will you have a dedicated account representative?
- Is technical support available outside normal business hours?
- Who handles terminal or gateway issues?
- Who can explain a funding problem?
- Who helps when a chargeback arrives?
- Can someone review an unfamiliar line item on your statement?
BAMS currently provides merchants with a dedicated account representative, in-office support and 24/7 technical support options, along with an online support system. BAMS also publishes dedicated support contacts for gateway and terminal issues.
PCI Compliance Is a Good Test of Support Quality
PCI compliance is a good example of why knowledgeable merchant support matters.
Businesses accepting payment cards have responsibilities under the Payment Card Industry Data Security Standard, or PCI DSS.
Those responsibilities do not disappear simply because a merchant uses an outside processor or payment gateway.
The PCI Security Standards Council states that merchants outsourcing payment functions remain responsible for understanding shared responsibilities, monitoring the compliance status of relevant service providers and completing their applicable PCI validation.
A good payment partner should therefore do more than say, “We’re PCI compliant.”
It should help the merchant understand what its own business needs to do.
BAMS currently provides PCI compliance support, including guidance around questionnaires, secure gateways, EMV transactions and payment-data security.
Support Extends Beyond Security
The processor can also become an important partner when the business deals with fraud, disputes, equipment problems or unexpected account activity.
For example, BAMS merchants currently have access to chargeback management tools that provide dispute notifications, case-specific action checklists and online response management.
Those services may not matter on the day the account opens.
They matter when the first problem appears.
3) Failing to Consider Funding
How quickly a payment processor makes funds available can have a direct effect on a company’s cash flow.
Card authorization and bank deposit are two different events.
A customer can complete a purchase successfully while the merchant still waits several business days for the associated revenue to reach its bank account.
Visa currently notes that funding time varies by merchant-services provider and describes three to five business days as an industry-average funding period for traditional merchant services. :contentReference[oaicite:2]{index=2}
That delay may not matter much to every business.
For companies regularly turning sales back into payroll, inventory, advertising or supplier payments, it can matter considerably.
Ask About the Batch Cutoff
Funding speed is not just about whether the provider advertises “next-day funding.”
The cutoff time matters too.
A restaurant may generate much of its daily revenue after 6 PM. A processor with an early cutoff could technically advertise next-day funding while pushing a large portion of that restaurant’s transactions into a later deposit.
BAMS currently provides qualifying merchants with a 9 PM ET next-day funding cutoff.
Transactions submitted before that cutoff can reach the merchant’s bank account by approximately 7 AM the following business day, meaning eligible funds can arrive in as little as 10 hours.
BAMS also currently states that it does not charge an additional fee for its next-day funding service. :contentReference[oaicite:3]{index=3}
Funding Eligibility Still Matters
Faster funding is not necessarily available to every merchant.
BAMS notes that eligibility can depend on factors such as operating history, business type, fraud exposure and chargeback history.
That is why merchants should confirm funding terms before signing the processing agreement.
Ask:
- What is the standard funding schedule?
- What time is the batch cutoff?
- Am I eligible for next-day funding?
- Is same-day funding available?
- Are there additional funding fees?
- How are weekend batches handled?
- What happens around bank holidays?
The answers determine when processed sales become usable cash.
Do Not Evaluate These Three Areas Separately
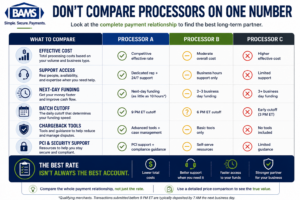
A useful payment processor comparison looks beyond the advertised rate to the complete merchant relationship.
Pricing, support and funding affect each other.
A processor with a slightly lower transaction rate may still be a poor fit if deposits arrive slowly and support is difficult to reach.
A provider with great support may still be too expensive if account fees push the effective processing rate well beyond competitive alternatives.
And fast funding may not justify a processor if merchants have to pay substantial extra charges to receive it.
The better comparison looks at the entire merchant account.
| What to Compare | What to Ask |
|---|---|
| Pricing | What is my total effective processing cost? |
| Pricing model | Can I see the processor markup separately from underlying costs? |
| Support | Who will help when something goes wrong? |
| PCI compliance | What help is available for my ongoing responsibilities? |
| Disputes | How will I be notified and how do I respond? |
| Funding | When will my money reach the bank? |
| Batch cutoff | How late can transactions be submitted for the fastest funding? |
| Funding fees | Does faster access cost extra? |
Look at What Happens After the Sale
Merchants naturally focus on checkout because that is the part customers see.
But much of the value of a payment processor becomes visible after the customer leaves.
How quickly does the money settle?
Can you find the transaction in reporting?
Can someone explain an unexpected fee?
Will you receive immediate notice if the customer disputes the charge?
Can the processor help if the terminal stops working?
Those questions help distinguish a payment-processing relationship from a transaction rate.
Frequently Asked Questions
What should businesses look for in a payment processor?
Businesses should compare total processing cost, pricing structure, funding speed, customer support, PCI compliance assistance, dispute-management tools and compatibility with the POS, gateway or eCommerce platform they use.
Is the lowest payment processing rate always the best option?
No. A low advertised rate can be offset by monthly charges, transaction fees, gateway costs, chargeback fees or slower funding. Compare the total effective cost and the services included.
Are PayPal, Stripe and Square always more expensive than traditional merchant accounts?
No. Payment service providers can be practical for businesses that value simple setup and bundled services. Traditional merchant accounts may become more economical as payment volume increases or when a business needs more customized pricing and payment infrastructure.
What is interchange-plus pricing?
Interchange-plus pricing separates the underlying interchange cost from the payment processor’s markup. This can make the pricing structure easier for merchants to understand and audit.
Why is payment-processing support important?
Support can become critical when merchants encounter funding issues, chargebacks, PCI compliance questions, gateway problems or payment-terminal failures. A strong processor should provide a clear path for getting those problems resolved.
How quickly should a payment processor deposit funds?
Funding schedules vary by provider and merchant account. Some processors follow multi-day funding schedules, while qualifying BAMS merchants can currently receive eligible next-day deposits in as little as 10 hours.
What is a batch cutoff?
The batch cutoff is the time by which a merchant must submit its daily group of transactions to qualify for a particular settlement schedule. BAMS currently uses a 9 PM ET cutoff for qualifying next-day funding.
Does BAMS charge extra for next-day funding?
BAMS currently states that its next-day funding program carries no additional transfer fees for qualifying merchants.
Do payment processors handle PCI compliance for merchants?
Processors and third-party providers can help reduce PCI scope and provide compliance tools, but merchants retain their own PCI DSS responsibilities. The exact requirements depend on the business’s payment environment.
Choose the Complete Payment Relationship
New and experienced merchants alike stand to gain from choosing a merchant-services provider based on more than one advertised processing rate.
BAMS currently combines transparent pricing with next-day funding options, dedicated merchant support, PCI compliance assistance, chargeback management and reporting tools. Its merchant-account pricing also includes custom interchange-plus options for businesses with larger payment volumes or more complex needs. :contentReference[oaicite:4]{index=4}
The best way to know whether a new processor can actually save money is to compare it against what the business pays today.
If you’re ready to see how a BAMS merchant account compares with your current payment processing setup, start your free five-point price comparison.