Why Is Interchange-Plus Pricing the Most Advantageous Merchant Account Pricing Format?
Last Updated on September 4, 2026 by Dimitri Akhrin
Interchange-Plus Makes It Easier to See What Payment Processing Actually Costs
A merchant’s profitability is determined in part by the costs of doing business, and one of the most common expenses merchants face is the cost of processing card payments.
But payment processing is not priced the same way everywhere.
Some providers use standardized flat rates. Others group transactions into broader pricing tiers. Another option is interchange-plus pricing, which separates the underlying interchange associated with a transaction from the payment processor’s markup.
That separation is what makes interchange-plus particularly valuable.
A merchant can see more clearly which costs originate in the card-payment ecosystem and which portion represents the processor’s pricing. That makes statements easier to audit and processor markup easier to compare.
BAMS offers interchange-plus pricing for merchants that want greater visibility into their payment costs, along with a Competitive Price Guarantee for qualifying merchant account offers.
TL;DR
- Interchange-plus pricing separates underlying card costs from processor markup – Instead of blending everything into one standardized rate, merchants can see the interchange associated with a transaction separately from what the payment provider charges above it.
- Interchange varies because card transactions do not all cost the same – Card type, debit regulation status, merchant category, payment channel, clearing timing and transaction data can all affect how a transaction qualifies.
- The biggest advantage is transparency – Merchants can more easily identify processor markup, review changes in transaction mix and audit monthly statements when underlying costs and provider pricing are shown separately.
- Interchange-plus is not automatically the cheapest option – A poorly priced account can still be expensive once processor markup, gateway fees, monthly charges, funding terms and chargeback costs are included. The complete merchant account should be compared.
- Optimization matters in addition to pricing structure – Merchants generally cannot negotiate published interchange schedules, but certain transactions may qualify differently depending on how they are processed. B2B merchants can also use eligible Level 2 and Level 3 data to help transactions reach more favorable interchange categories.
What Is Interchange-Plus Pricing?
Interchange-plus is a payment-processing pricing model built around two primary components:
- Interchange: the underlying interchange reimbursement amount associated with the card and transaction.
- Processor markup: the agreed fee the payment provider charges above the underlying payment costs.
The result is a pricing structure where the processor’s markup can be separated from the interchange associated with each transaction.
For example, rather than charging one standardized 2.9% rate regardless of which card is used, an interchange-plus account might pass through the applicable interchange category and then add an agreed processor percentage and transaction fee.
If the underlying interchange is lower, the merchant can benefit from that lower cost rather than automatically paying the same standardized percentage.
Interchange-Plus Does Not Mean There Are Only Two Fees
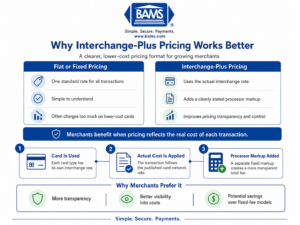
Interchange-plus pricing makes it easier to distinguish underlying card costs from the payment processor’s markup.
This is an important clarification to the original article.
The phrase “interchange-plus” describes the pricing model, but interchange and processor markup are not necessarily the only costs associated with accepting a card.
A merchant’s complete processing cost can include:
- Interchange
- Card-network assessments and related network fees
- Processor markup
- Per-transaction charges
- Gateway or account fees
- Chargeback and dispute-related costs
- Other services associated with the merchant account
That is why merchants should still review the complete merchant statement rather than assuming that any account labeled “interchange-plus” is automatically inexpensive.
What Is the Interchange Rate?
Interchange is one component of the economic model behind card payments.
Visa describes its interchange reimbursement fees as transfer fees between financial institutions. Mastercard similarly explains that interchange is generally paid by the merchant’s acquiring side to the financial institution that issued the customer’s card.
The merchant itself generally pays a merchant discount or processing cost to its acquiring or payment-services provider rather than sending interchange directly to the issuing bank.
That distinction matters because interchange is only one component of what appears on the merchant’s total processing bill.
Who Sets Interchange?
Card networks including Visa and Mastercard establish and publish their applicable interchange programs.
Those programs contain many different categories rather than one universal Visa or Mastercard percentage.
Mastercard notes that its interchange qualification criteria can include merchant category, authorization and clearing timing, payment data submitted, how the card is presented and merchant transaction volume.
Visa’s current rate tables likewise contain different programs based on card type, transaction channel, merchant category and other transaction characteristics.
Why Do Interchange Rates Vary?

The dollar amount of a sale is only one factor that can influence interchange qualification.
Two transactions for the exact same dollar amount can carry different underlying interchange.
Some of the factors that may influence the applicable category include:
- Whether the card is credit, debit or prepaid
- Whether debit is regulated or exempt
- The type or rewards level of the card
- The merchant’s industry or merchant category code
- Whether the card is present
- Whether the transaction takes place online or is manually keyed
- How quickly the transaction is submitted for clearing
- Whether required transaction data is provided
That variability is one of the main reasons interchange-plus pricing can make sense.
If the underlying transaction costs are different, the merchant-facing pricing can reflect those differences instead of blending everything into one standardized rate.
A Current 2026 Visa Example
Visa’s current U.S. interchange reimbursement schedule became effective April 18, 2026.
One simple example shows how much context matters.
| Visa Debit Transaction | Exempt Visa Check Card | Regulated Visa Check Card |
|---|---|---|
| Card-Present Retail | 0.80% + $0.15 | 0.05% + $0.21* |
| Card-Present Restaurant | 1.19% + $0.10 | 0.05% + $0.21* |
| Retail Key Entry | 1.65% + $0.15 | 0.05% + $0.21* |
*Additional Visa conditions and qualifications apply. Rates shown are examples from Visa’s U.S. schedule effective April 18, 2026 and should not be interpreted as the total merchant processing cost.
The card might still say Visa Debit in every example, but how the transaction qualifies changes the underlying interchange.
This is why quoting one generic “Visa rate” does not accurately describe the cost of accepting Visa cards.
How Does Interchange-Plus Pricing Benefit Merchants?
The strongest benefit of interchange-plus is transparency.
Because interchange and processor markup can be separated, the merchant has a clearer view of where payment costs come from.
That creates several practical advantages.
1. Lower-Cost Transactions Can Remain Lower Cost
With standardized flat-rate pricing, the merchant generally pays the same processor rate even when the underlying transaction is relatively inexpensive.
Interchange-plus allows the merchant-facing cost to change with the applicable interchange category.
A low-cost debit transaction does not necessarily have to carry the same merchant-facing percentage as a higher-cost rewards credit card.
2. The Processor Markup Is Easier to See
This may be the most important long-term advantage.
Merchants usually cannot negotiate Visa or Mastercard’s published interchange schedule directly.
They can negotiate what their processor charges above those underlying costs.
Interchange-plus makes that distinction clearer.
If one provider charges interchange plus 0.40% while another offers interchange plus 0.25%, the processor portion of the comparison is much easier to identify than it would be inside two different bundled-rate structures.
3. Statements Become Easier to Audit
A transparent pricing model gives merchants more information when reviewing monthly statements.
You can examine how transaction mix changes from month to month and separate underlying card costs from the portion controlled by the payment processor.
That can also make unexpected increases easier to investigate.
4. Pricing Can Scale Better With Volume
Small differences become increasingly important as transaction volume grows.
A difference of 0.25 percentage points represents:
| Annual Processing Volume | 0.25% Difference |
|---|---|
| $100,000 | $250 |
| $500,000 | $1,250 |
| $1,000,000 | $2,500 |
| $5,000,000 | $12,500 |
Those figures are illustrations rather than guaranteed savings. Actual costs depend on card mix, transaction channel, processor markup and other account fees.
They do show why established merchants should care about fractions of a percentage point.
Flat Rate vs Interchange-Plus Pricing
Flat-rate pricing is not inherently bad.
Its main advantage is simplicity.
Stripe, for example, currently publishes standard U.S. domestic-card pricing of 2.9% + $0.30 per successful transaction. A merchant can understand that number quickly and forecast costs without reviewing dozens of interchange categories.
Stripe also offers interchange-plus pricing and volume discounts through customized packages for businesses with larger payment volumes or unique payment requirements.
That illustrates an important point: as businesses scale, payment pricing often becomes more customized.
| Feature | Flat Rate | Interchange-Plus |
|---|---|---|
| Simplicity | Very easy to understand | More detailed |
| Predictability | High | Varies with transaction mix |
| Interchange visibility | Usually blended | Separated |
| Processor markup visibility | Usually blended | Easier to identify |
| Lower-cost transactions | Generally pay the standardized rate | Can benefit from lower underlying interchange |
| Best fit | Businesses prioritizing simplicity | Businesses prioritizing transparency and cost optimization |
What Happened to the “Float Room”?
The original version of this article used the phrase “float room” to describe the difference between a processor’s standardized flat rate and the underlying cost associated with lower-interchange transactions.
The idea is useful, but a clearer term is blended pricing margin.
A flat-rate provider has to set pricing that works across a wide variety of cards and transactions. Some transactions cost the provider more and others cost less.
The merchant generally pays the standardized rate either way.
With interchange-plus, the variable underlying cost is passed through separately and the processor markup is disclosed on top of it.
That does not guarantee that every interchange-plus account is cheaper. It does make the pricing mechanics easier to inspect.
Interchange-Plus Is Not Automatically the Cheapest Account
This is the most important qualification to add in 2026.
A processor could technically offer interchange-plus pricing while adding a large markup, expensive gateway fees or unnecessary monthly charges.
Meanwhile, another provider could offer a competitive bundled rate that works extremely well for a particular merchant.
Do not choose a processor simply because the proposal says “interchange-plus.”
Compare:
- The processor percentage markup
- The processor transaction fee
- Monthly account charges
- Gateway costs
- PCI-related fees
- Funding terms
- Chargeback costs
- Hardware or software expenses
The goal is the lowest appropriate total cost, not simply the most attractive pricing-model label.
Calculate Your Effective Processing Rate
Your merchant statement can tell you whether the account is actually competitive.
Use: Total payment-processing costs ÷ total card-processing volume × 100 = effective processing rate
Track that figure over several months.
If the effective rate moves substantially, investigate what changed. Card mix, transaction channel, account fees or processor pricing could all contribute.
Interchange Optimization Matters Too
Interchange is often described as completely fixed, but merchants can sometimes influence which interchange category a transaction qualifies for.
The published rates themselves are generally established by the card networks. Qualification can depend on how the transaction is processed.
Mastercard specifically notes factors such as merchant category, authorization-to-clearing timing, payment data and transaction volume when determining interchange qualification.
For B2B businesses, submitting the correct enhanced transaction information can be particularly important.
BAMS’ Level 2 and Level 3 processing solutions can automatically populate eligible transaction data to help qualifying commercial-card transactions reach more favorable interchange categories.
That means merchants should look at both pieces:
What interchange category are my transactions qualifying for, and what markup is my processor charging above it?
How BAMS Approaches Interchange-Plus Pricing
BAMS currently offers interchange-plus pricing and custom pricing for businesses with larger payment volume or more complex payment needs.
The goal is to separate underlying transaction costs from the processor’s pricing so merchants have greater visibility into how the account is structured.
BAMS also offers a five-step Merchant Account Price Comparison.
The process starts with the merchant’s current statement and reviews the account line by line, including account classification, current fees, payment acceptance setup and opportunities to reduce unnecessary costs.
BAMS now backs qualifying merchant pricing with its Competitive Price Guarantee. If an eligible merchant receives an official lower merchant-account fee schedule from another registered financial services provider, BAMS states that it will match or beat the qualifying offer.
Frequently Asked Questions
What is interchange-plus pricing?
Interchange-plus is a payment-processing pricing model that separates the applicable interchange associated with a card transaction from the processor’s agreed markup.
Who receives interchange?
Interchange is generally transferred from the acquiring side of the transaction to the financial institution that issued the customer’s card. The merchant normally pays its processor or acquiring provider rather than paying interchange directly to the issuer.
Who sets interchange rates?
Card networks such as Visa and Mastercard establish their applicable interchange programs and publish rate schedules and qualification criteria.
Why do interchange rates vary?
Rates can vary based on card type, debit regulation status, merchant category, how the payment is accepted, transaction data and other qualification requirements.
Is interchange-plus always cheaper than flat-rate pricing?
No. Interchange-plus can be especially valuable for transparency and may reduce costs for many merchants, but the outcome depends on processor markup, transaction mix and other account fees.
Can merchants negotiate interchange?
Merchants generally cannot negotiate the card networks’ published interchange rates directly. They may be able to optimize how eligible transactions qualify and can negotiate the markup charged by their payment processor.
What is processor markup?
Processor markup is the portion of the processing price charged by the merchant-services provider above underlying payment costs. In interchange-plus pricing, this markup is generally easier to identify separately.
Does interchange-plus include network fees?
Not necessarily. Card-network assessments and other charges can exist in addition to interchange and processor markup. Merchants should review the full fee schedule and statement.
Why is interchange-plus considered transparent?
It separates the variable interchange associated with individual transactions from the processor’s markup, giving merchants more information about which costs come from the payment ecosystem and which are controlled by the processor.
Transparency Gives Merchants More Control
The biggest advantage of interchange-plus pricing is not a promise that every transaction will always be the cheapest possible.
It is visibility.
Merchants can see the underlying interchange associated with their transactions, identify the processor markup and evaluate whether the overall merchant account remains competitive as the business grows.
That makes it easier to audit statements, negotiate pricing and understand how card mix affects payment costs.
If you want to see how BAMS’ interchange-plus pricing compares with your current processing setup, request a free five-step Merchant Account Price Comparison. BAMS will review your current merchant statement line by line and identify areas where payment costs may be reduced.