Card Dipping: What You Should Know
Last Updated on October 5, 2026 by Dimitri Akhrin
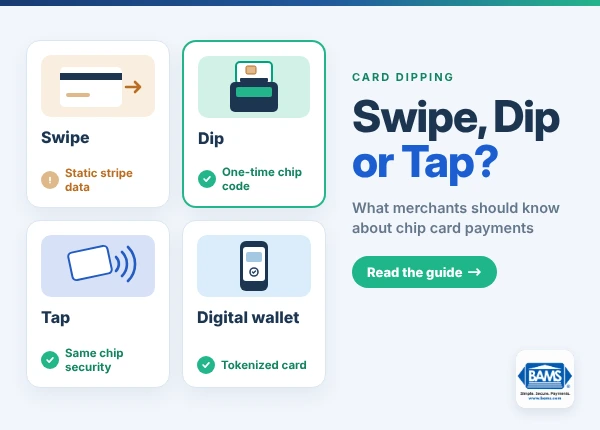
Card dipping isn’t a term most people know. But if you’ve ever inserted a credit or debit card into a chip-enabled EMV payment terminal or ATM, you’ve dipped. Swiping is the oldest way to pay with a card. Tapping is the contactless method many shoppers now prefer. Dipping sits in between.
TL;DR
- Dipping uses the card’s chip – The chip creates a unique code for each purchase, which makes stolen data much harder to reuse.
- Chip acceptance protects merchants – Since the 2015 liability shift, the party that can’t process a chip card can be liable for counterfeit fraud.
- Dipping doesn’t automatically lower fees – Card-present pricing depends on the card type and your pricing plan, not just how the card is read.
- Chip cards still have weak spots – Swipe fallback and card skimmers remain common ways thieves try to get around the chip.
- Tap and digital wallets add security – They use the same chip security and digital wallets also hide the real card number.
What Happens When You Dip Your Card?
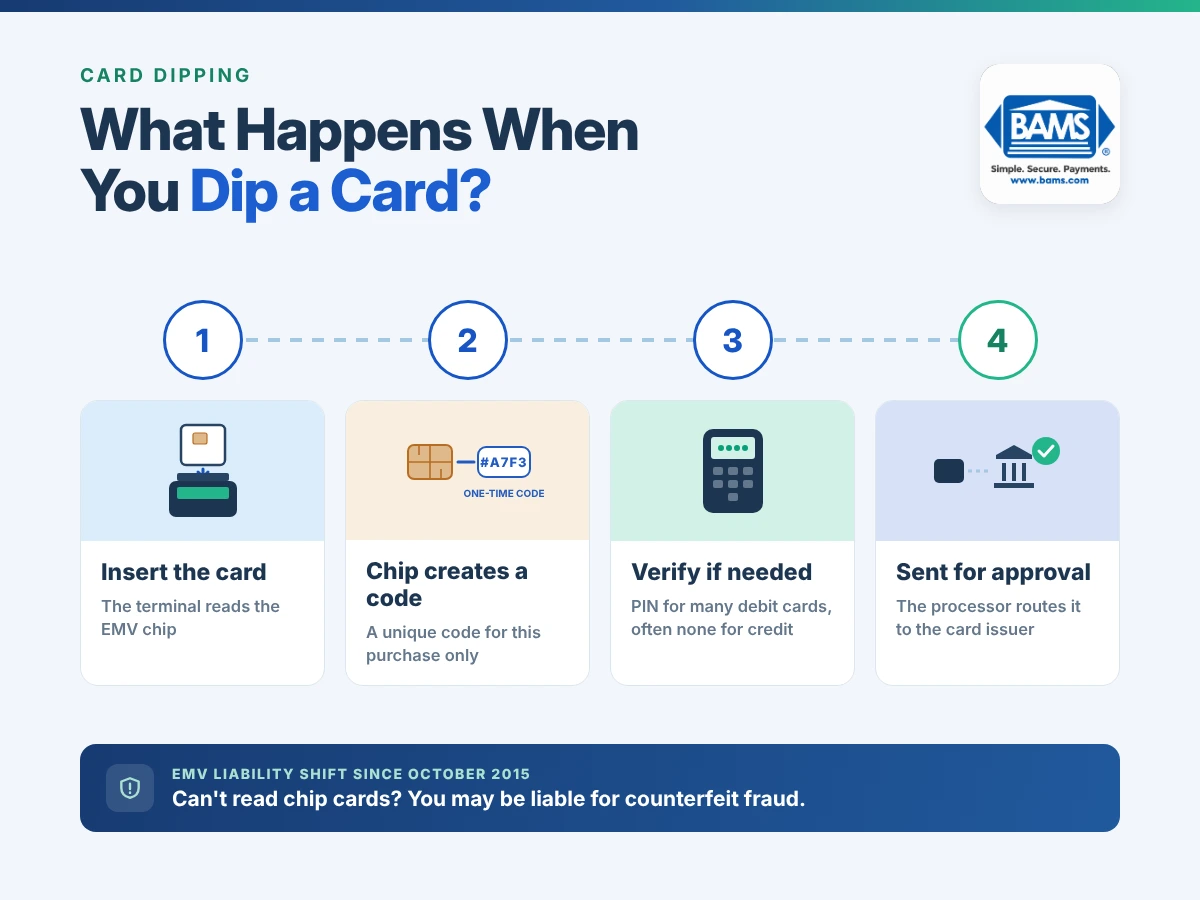
When you dip a debit or credit card, the terminal reads payment data from the card’s embedded microchip. The chip does more than store the same data as the magnetic stripe. For each purchase, it creates a one-time code that the card issuer can verify.
The terminal may then ask for verification. That depends on the card and the merchant’s setup. Debit cards often call for a PIN. Many credit card purchases need no PIN or signature at all. Once verification is complete, the terminal sends the payment to the processor for approval.
Swiping the stripe was once the undisputed king of electronic payments. Today, dipping and tapping are far more common. Many merchants prefer them thanks to the benefits they offer.
The Benefits of Card Dipping
The biggest problem with swiping is that the magnetic stripe holds static data. A thief who copies it can create a counterfeit card. Signatures never did much to stop that, since they’re easy to forge.
Dipping solves much of that problem. Visa’s merchant guide to chip cards explains that the chip generates a unique code that is virtually impossible to counterfeit. Even if a thief steals data from one chip transaction, that code won’t work again.
Chip acceptance also matters for liability. The liability shift began in October 2015. Since then, the party that blocks a chip transaction can be liable for card-present counterfeit fraud. If a customer has a chip card and your terminal can’t read it, that risk may fall on you.
Does Dipping Lower Your Fees?
Not by itself. Chip, swipe and tap transactions are all card-present payments. Your cost depends mainly on the card type, the transaction and your pricing model. The way the card is read isn’t usually the deciding factor. Keyed-in transactions can cost more, though. Fraud losses and chargebacks also add real costs of their own. With transparent interchange plus pricing, your statement shows the cost of each card type.
Downsides of Card Dipping
Dipping is not a perfect solution. Chip cards are more secure than swiping, but thieves can still exploit them.
The easiest exploit is simple. A thief claims the chip on a stolen card is broken and asks to swipe instead. That move gives up the chip’s security benefits. Visa notes that chip cards keep a magnetic stripe so they work at terminals without a chip reader. That fallback is useful, but staff should treat repeated chip failures with caution.
Card skimmers are another threat. These fake card readers sit on top of real payment hardware and capture card details. Paired with small cameras, skimmers on gas pumps and ATMs can capture both card data and PINs.
Better Alternatives: Tap and Digital Wallets
Contactless payments combine chip-level security with the speed of a quick tap. According to Visa’s overview of contactless payments, tap transactions use the same security as contact chip cards. Shoppers can tap a contactless card or a payment-enabled phone or wearable.
Digital wallets like Apple Pay and Google Pay add another layer. Users load their payment cards onto their phones or watches. Each payment then needs a fingerprint, face scan or passcode on the device.
Digital wallets also use tokenization. Mastercard’s guide to tokenization explains that a stand-in number replaces the real card number. The actual card information is never shared at checkout. Each transaction also gets a one-time code, which makes it very hard for a thief to make an unauthorized in-store payment.
Accept Dip, Tap and Digital Wallets with BAMS
BAMS offers a full range of EMV-compliant payment hardware that accepts both dip and tap payments. BAMS also supports digital wallets like Apple Pay. That lets you give customers convenient and secure ways to pay.
Card Dipping FAQs
What does it mean to dip a card?
Dipping means inserting a chip card into a payment terminal so the terminal can read the card’s EMV chip.
Is dipping safer than swiping?
Yes. The chip creates a unique code for each transaction, so stolen data is much harder to reuse than magnetic stripe data.
Is tapping less secure than dipping?
No. Contactless payments use the same security as contact chip cards. Digital wallets add tokenization and device authentication.
Do chip transactions cost merchants less?
Not automatically. Card-present pricing depends mainly on the card type and your pricing plan. Chip acceptance mainly helps you avoid counterfeit fraud liability.
What is the EMV liability shift?
Since October 2015, the party that causes a chip transaction not to happen can be liable for card-present counterfeit fraud losses.
Sources
- Visa – Tap Into the Power of Chip: Merchant Guide
- Visa – What Are Contactless Payments?
- Mastercard – What Is Tokenization?
Want to see how your current hardware and processing costs compare? Request a free five-point Merchant Account Price Comparison.