Is A Flat Rate Good for Your Business? – Spoiler: Probably Not!
Last Updated on September 4, 2026 by Dimitri Akhrin
Simple Pricing Can Be Useful, but Simpler Does Not Always Mean Cheaper
What makes a reasonable transaction fee?
A surprising number of merchants never really answer that question. They know the rate printed on the processor’s website but not necessarily what accepting payments costs their business over an entire month.
That is one reason flat rate payment processing is so appealing.
The pricing is straightforward. A processor charges the same basic percentage and transaction fee regardless of the underlying interchange cost of the card used. That makes bills easier to estimate and removes much of the complexity from card processing.
For some businesses, that simplicity is valuable enough to make flat-rate pricing a good fit.
For others, particularly merchants processing significant volume, charging the same flat rate across transactions can mean paying considerably more than necessary.
The question in 2026 is not whether flat-rate pricing is good or bad. It is whether the simplicity is worth what your particular business pays for it.
TL;DR
- Flat-rate pricing trades cost detail for simplicity – Merchants pay a standardized percentage and transaction fee even though the underlying cost of card transactions can vary. That predictability can be useful for businesses that prioritize simple pricing.
- Flat-rate pricing can become less efficient as payment volume grows – Small differences in processing cost can add up across hundreds of thousands or millions of dollars in annual card volume, especially when many transactions carry lower underlying interchange costs.
- There is no universal volume threshold for switching pricing models – Monthly volume alone does not determine whether flat-rate or interchange-plus pricing is better. Card mix, average ticket, transaction count and account-level fees can all change the result.
- Your effective processing rate is a better comparison tool than one advertised percentage – Compare total processing costs against total card volume and include transaction fees, gateway costs, monthly charges, PCI-related fees and chargeback costs.
- Interchange-plus provides more visibility into how processing costs are built – It separates the underlying interchange associated with each transaction from the processor markup, making it easier to evaluate whether the simplicity of flat-rate pricing is still worth the cost to your business.
What Is Flat Rate Payment Processing?
Flat-rate pricing charges a standardized processor rate instead of changing the merchant-facing price according to the interchange category associated with each card transaction.
Stripe is a straightforward current example. Its standard U.S. pricing for domestic card transactions is 2.9% plus $0.30 per successful transaction.
That same standard rate generally applies whether the customer pays using a basic consumer card or a card carrying a higher underlying interchange cost.
PayPal also uses standardized pricing for several of its payment products, although it no longer has one universal merchant rate.
As of September 2026, PayPal’s published U.S. rates include:
- 2.99% + $0.49 for standard credit and debit card payments
- 3.49% + $0.49 for PayPal Checkout
- 2.89% + $0.29 for Advanced credit and debit card payments
PayPal now also offers an interchange-plus-plus pricing option for eligible Advanced card-payment accounts, showing that the distinction between traditional merchant accounts and payment service providers is not as rigid as it once was.
Who Is Flat Rate Pricing Good For?
Flat-rate pricing can work particularly well for merchants that place a high value on simplicity.
That often includes businesses just starting to accept cards, merchants processing relatively low payment volume and companies that would rather have an easy-to-understand payment setup than optimize every fraction of a percentage point.
There are several legitimate advantages.
1. Pricing Is Easy to Understand
If the processor charges 2.9% plus $0.30, a merchant can estimate transaction costs without understanding interchange categories or card-network pricing.
That makes forecasting easier.
2. Setup Can Be Simple
Flat-rate payment service providers often bundle processing with checkout, gateway functionality, fraud tools, reporting and other services.
A small business can sometimes begin accepting payments without assembling several separate payment products.
3. There May Be Fewer Account-Level Decisions
Traditional merchant pricing can require merchants to compare processor markup, gateway charges, transaction fees and other account terms.
A bundled flat-rate platform may reduce those decisions.
That convenience has real value, especially when processing volume is still small enough that optimizing card costs is not a major financial priority.
What Makes Flat Rates Less Efficient as a Business Grows?
The weakness of flat-rate pricing is the same thing that makes it attractive: the price does not change much when the underlying transaction cost does.
Card transactions do not all cost the same amount to process.
Interchange can vary based on factors such as:
- Card type
- Credit versus debit
- Rewards level
- How the payment is entered
- Merchant category
- Transaction characteristics
A flat-rate processor absorbs those differences and charges merchants a standardized rate.
That creates predictability but it also means lower-cost transactions do not necessarily result in a lower merchant-facing rate.
Volume Makes Small Differences Bigger
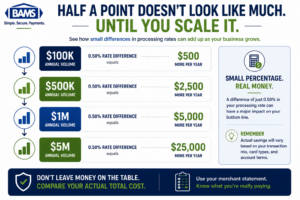
Small differences in processing costs can become significant as annual card volume grows.
A fraction of a percentage point may not look meaningful on one transaction.
Across significant annual payment volume, it can become substantial.
Consider the percentage component alone:
| Annual Card Volume | 0.25% Difference | 0.50% Difference |
|---|---|---|
| $100,000 | $250 | $500 |
| $500,000 | $1,250 | $2,500 |
| $1,000,000 | $2,500 | $5,000 |
| $5,000,000 | $12,500 | $25,000 |
Those numbers do not represent guaranteed savings from switching pricing models. They simply show why merchants processing higher volume should pay attention to differences that initially look small.
There Is No Universal $5,000 Monthly Crossover Point
The original version of this article suggested that businesses should generally move away from flat-rate pricing once they process $5,000 per month.
That is too simplistic.
Two merchants processing exactly $5,000 can have completely different economics.
One could process five $1,000 transactions while another processes 500 $10 transactions. The per-transaction component alone makes those accounts very different.
Card mix also matters.
One merchant may receive a large percentage of lower-cost debit cards while another serves customers using premium rewards cards. Card-present and card-not-present transactions can carry different costs as well.
There is no single revenue number that tells every business when to switch.
The better approach is to compare your actual merchant statement.
Do the Math Using Your Effective Processing Rate
Instead of focusing on one advertised rate, calculate what processing actually costs.
Total payment processing costs ÷ total card volume × 100 = effective processing rate
Include relevant processor fees rather than looking only at the percentage charged on individual sales.
That may include:
- Percentage processing fees
- Per-transaction fees
- Gateway costs
- Monthly account fees
- PCI-related fees
- Chargeback fees
- Other recurring payment costs
Once you know the effective rate, you have something useful to compare against another processor.
What Is the Alternative to Flat Rate Pricing?
One common alternative is interchange-plus pricing.
With interchange-plus, the pricing is separated into two main pieces.
The first is the underlying interchange associated with the transaction. The second is the processor’s agreed markup.
Instead of blending both components into one standardized flat rate, the merchant can see them separately.
A Simple Example
Imagine two card transactions with different underlying interchange costs.
Under a flat-rate model, the merchant might pay the same standardized rate on both.
Under interchange-plus, each transaction reflects its actual interchange category plus the processor’s markup.
That means a lower-cost transaction can remain lower cost to the merchant rather than being automatically priced at the same percentage as a more expensive card.
Interchange-Plus Is About Transparency as Much as Cost
One of the strongest arguments for interchange-plus is not that it magically makes every transaction cheap.
It is that the merchant can see more clearly how the price is constructed.
BAMS’ current merchant account pricing uses transparent interchange-plus pricing for eligible accounts. The underlying interchange and the processor markup can be reviewed separately rather than being blended into one broad rate.
BAMS’ recently updated comparison of tiered and interchange-plus pricing makes the same point: the lowest advertised transaction rate does not automatically produce the lowest overall cost once monthly fees, gateway costs, funding and dispute expenses are included.
Interchange-Plus Is Not Automatically Cheaper for Every Business
This is another important correction to the original article.
Interchange-plus can produce meaningful savings for many established or higher-volume merchants but it should not be described as automatically cheaper for everyone.
A traditional merchant account may include costs that a bundled payment service provider does not.
The processor markup also matters.
A poorly priced interchange-plus account could still be more expensive than a competitive flat-rate option.
The comparison needs to be made account against account.
Flat Rate vs Interchange-Plus
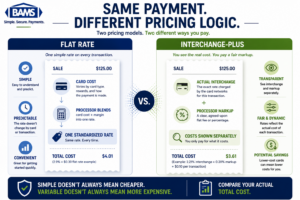
Flat-rate pricing prioritizes simplicity while interchange-plus separates underlying card costs from the processor markup.
| Feature | Flat Rate | Interchange-Plus |
|---|---|---|
| Pricing simplicity | Very straightforward | More detailed |
| Predictability | High | Varies with transaction mix |
| Interchange visibility | Usually blended into the rate | Shown separately |
| Processor markup visibility | Usually blended | Generally separated |
| Lower-cost cards | Typically charged the standardized rate | Can reflect the lower interchange category |
| Best fit | Merchants prioritizing simplicity and predictable pricing | Merchants prioritizing transparency and cost optimization |
Even Major Flat-Rate Providers Offer Custom Pricing at Scale
There is a useful clue in how today’s major payment platforms structure their own pricing.
Stripe publishes its familiar standard rate of 2.9% plus $0.30 for domestic cards but also offers custom packages for businesses with large payment volume or unique business models.
Those custom packages can include volume discounts and interchange-plus pricing.
PayPal also now offers interchange-plus-plus pricing for eligible Advanced credit and debit card payment accounts.
That does not mean every growing merchant needs to abandon flat-rate pricing.
It does show that payment pricing often becomes more customized as businesses scale.
Average Ticket Size Matters Too
Merchants often focus on the percentage and overlook the fixed transaction fee.
That can make a significant difference for businesses selling lower-priced products.
Consider a processor charging $0.30 per transaction.
On a $10 purchase, the fixed fee alone represents 3% of the sale before the percentage fee is added.
On a $100 purchase, the same $0.30 represents only 0.3%.
That is why two merchants processing the same monthly volume can have very different payment costs.
Transaction count and average ticket matter alongside total volume.
What Should Merchants Compare?
Before choosing between flat-rate and interchange-plus pricing, review the entire payment relationship.
| Question | Why It Matters |
|---|---|
| What is my effective processing rate? | Shows what processing actually costs rather than one advertised percentage. |
| What is my average ticket? | Fixed transaction fees have a larger impact on smaller purchases. |
| What cards do my customers use? | Interchange varies across card and transaction types. |
| How much do I process? | Small pricing differences become more significant at higher volume. |
| What other fees apply? | Gateway, monthly and dispute costs can change the overall comparison. |
| What services are included? | Bundled tools can have value even if the transaction rate is higher. |
Use Your Actual Merchant Statement
The easiest way for an established business to decide whether flat-rate pricing is still competitive is to stop working from hypothetical numbers.
Use your processing statement.
BAMS offers a five-step merchant account price comparison that starts with the merchant’s existing statement.
The BAMS team reviews the account line by line, checks the business classification and compares current fees against a proposed merchant account structure.
BAMS also backs qualifying pricing with its Competitive Price Guarantee. If an eligible merchant receives a qualified lower merchant-account fee schedule from another registered financial services provider, BAMS states that it will match or beat the offer.
Frequently Asked Questions
What is flat rate payment processing?
Flat-rate payment processing charges a standardized merchant-facing percentage and transaction fee rather than pricing each transaction according to its individual interchange category.
Is flat-rate payment processing bad?
No. Flat-rate pricing can be useful for businesses that prioritize simplicity, predictable costs and easy onboarding. It can become less efficient for some merchants as payment volume grows.
How much does Stripe charge in 2026?
Stripe currently publishes a standard U.S. rate of 2.9% plus $0.30 for successful domestic card transactions. Custom pricing is available for larger businesses and can include interchange-plus and volume discounts.
How much does PayPal charge in 2026?
PayPal’s rates vary by payment product. Its current U.S. published rates include 2.99% plus $0.49 for standard credit and debit card payments, 3.49% plus $0.49 for PayPal Checkout and 2.89% plus $0.29 for Advanced card payments.
What is interchange-plus pricing?
Interchange-plus separates the underlying interchange cost associated with the transaction from the payment processor’s agreed markup.
Is interchange-plus always cheaper than flat-rate pricing?
No. The result depends on card mix, transaction volume, average ticket, processor markup and other account fees. Many higher-volume merchants may benefit from interchange-plus but the correct comparison should use the complete merchant account.
When should a business switch away from flat-rate pricing?
There is no universal monthly-volume threshold. Merchants should compare pricing when processing costs become material enough to justify optimization or when transaction volume, card mix or payment needs change.
Is $5,000 per month the point where flat-rate processing becomes too expensive?
No. The original version of this article used $5,000 as a rule of thumb but there is no universal crossover point. The result depends on the merchant’s transaction profile and competing account terms.
Why does average ticket size matter?
A fixed per-transaction fee represents a larger percentage of a small purchase than a large one. Merchants processing many low-ticket transactions can therefore have very different costs from merchants processing the same volume through fewer large transactions.
Flat Rate Is a Convenience. Make Sure the Convenience Is Worth the Cost.
Flat-rate payment processing succeeds because it makes something complicated feel simple.
There is nothing inherently wrong with paying for that simplicity.
The mistake is continuing to pay a standardized rate without periodically checking whether it still makes sense for the business.
BAMS uses transparent interchange-plus pricing and provides merchants with a detailed comparison of their existing account so they can see how current processing costs compare. BAMS’ current pricing pages also emphasize looking beyond a headline rate to monthly fees, gateway costs, funding speed and dispute expenses when evaluating merchant services.
If your business has grown since you first chose a flat-rate processor, request a free five-step merchant account price comparison to see what your current payment structure is actually costing you.