Is Tiered Pricing as Good as Interchange Plus Pricing?
Last Updated on August 20, 2026 by Dimitri Akhrin
What Your Payment Pricing Model Really Changes
The pricing model behind a merchant account determines more than the rate shown on a proposal. It affects how easily you can see processing costs, how processor markup appears on your statement and how much information you have when comparing one provider with another.
Partnering with the right payment processor can be the difference between a healthy profit and financial struggle for merchants in a wide variety of industries. While the features offered by merchant services companies are important, low transaction fees are understandably the primary concern of most businesses, and an important step in securing the lowest fees possible is to understand the different pricing models available prior to signing a contract. In this article, we’ll look at one of the most common models, tiered pricing, and how it compares to the less common, but highly beneficial interchange plus pricing model.
What is Tiered Pricing?
Tiered pricing, also known as bundled pricing, is a pricing structure in which the payment processor allows merchants to bundle transactions into preset interchange-rate categories. For instance, credit card transactions might be bundled into one category with a set, bundled interchange-rate, and Visa or Mastercard debit cards might be grouped into a separate category with a different rate. Those tiers are often set as qualified, mid-qualified, and non-qualified transactions (referring to how transactions comply with card issuer rules), but the common factor is that, rather than charging a single rate across the board (or the actual interchange fee), tiered pricing uses consistent groupings with set prices.
There is an important distinction here. A processor’s pricing tier is not the same thing as a card network’s underlying interchange category. The processor decides how transactions fit into its pricing structure. That can make it harder for a merchant to separate the underlying card cost from the processor’s markup.
Interchange itself also varies. Modern Treasury explains that factors such as card type and transaction type can affect interchange fees. That variation is one reason the pricing model matters when you review a merchant statement.
What are the Benefits and Drawbacks of Tiered Pricing?
The benefit of tiered pricing is that, in some cases, it can offer lower transaction rates on certain sales, but only when compared with the high rates commonly offered by third-party payment processors like PayPal and Square. The downsides, on the other hand, are numerous. First, because the transactions are lumped into categories with a tier-wide rate set by the payment processor, merchants can’t see the actual interchange rates on their transactions. That makes tiered pricing opaque. More importantly, because the payment processor is setting the category rates, those rates are marked up to generate a profit. So, while tiered pricing might be cheaper than the extreme rates charged by third-party options, in general, it’s more expensive than it needs to be because the processors are making a profit on the actual interchange rates. Those charges are hidden, and a good rule of thumb is that hidden charges never work out in the merchant’s favor.
Where the Lack of Visibility Shows Up
The problem becomes easier to see when you look at a statement. A merchant may know the rate assigned to a qualified, mid-qualified or non-qualified tier without knowing exactly how the processor reached that number. That makes it difficult to tell how much of the charge came from interchange and how much came from processor pricing.
The underlying costs are not identical across every card transaction. The Federal Reserve’s debit interchange data shows differences across networks and between covered and exempt transactions. A pricing structure that exposes those differences gives a merchant more information to work with when reviewing costs.
That visibility matters when transaction volume grows. A small difference on one payment may seem insignificant. Spread across thousands of transactions, it becomes much easier to see why the pricing structure deserves attention.
Why Tiered Pricing Can’t Compete with Interchange-Plus Pricing
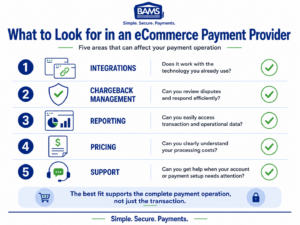
Online businesses should compare integrations, security, reporting, pricing and support when evaluating payment providers.
Interchange-plus pricing eliminates all of the problems associated with tiered pricing by basing transaction fees on the actual interchange rate charged on each individual transaction. The model offers some major advantages to merchants, both in their monthly bills and the level of insight they have into their own businesses. Because each transaction fee is based on the actual interchange rate levied by the card issuer, the savings from common, low-interchange cards, like Visa Debit, are passed directly to the merchant. That makes interchange-plus the cheapest pricing model currently available. Additionally, because each transaction fee is determined individually, merchants have full access to the exact interchange rates charged on each of their transactions, providing an accurate picture of their true costs, and enabling better financial management and decision making.
Interchange-plus does not make the underlying network cost disappear. What it changes is visibility. The processor can show the interchange component separately from its own markup rather than blending both into a tier.
Visa makes the distinction clear in its own pricing information. Visa explains that interchange reimbursement fees are transfer fees between acquiring and issuing banks. The merchant separately negotiates what Visa calls the merchant discount with its financial institution.
That separation is the practical reason many merchants prefer interchange-plus. You can see the underlying cost and then evaluate the processor’s markup on top of it.
BAMS provides transparent interchange plus pricing for merchants that want to see how processing costs are structured rather than relying on broad pricing tiers.
Tiered Pricing vs Interchange Plus at a Glance
| What to Compare | Tiered Pricing | Interchange Plus Pricing |
|---|---|---|
| Transaction grouping | Transactions are grouped into processor-defined pricing tiers. | Transactions reflect their individual interchange cost plus processor markup. |
| Interchange visibility | The underlying interchange cost can be difficult to separate from the tier rate. | The interchange component is shown separately from the processor markup. |
| Processor markup | Markup can be built into the rate assigned to each tier. | The processor markup can be identified more directly. |
| Statement analysis | Merchants may need more work to determine the true cost behind each tier. | Merchants can compare underlying card costs and processor pricing more directly. |
| Pricing simplicity | A few pricing tiers can look simple at first glance. | The statement may contain more detail, but that detail provides more cost visibility. |
Do Not Judge a Pricing Model by One Rate
A processor can advertise an attractive qualified rate while a large share of a merchant’s transactions ends up in more expensive tiers. That is why comparing only the lowest advertised percentage tells you very little about what the account will actually cost.
Look at the full statement instead. How many transactions fall into each category? What fees appear outside the transaction rate? Can you identify the processor markup? Can someone explain why a transaction received a particular rate?
The answers are more useful than one headline number.
What to Ask Before Choosing a Pricing Model
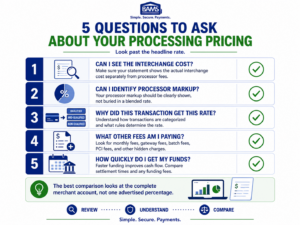
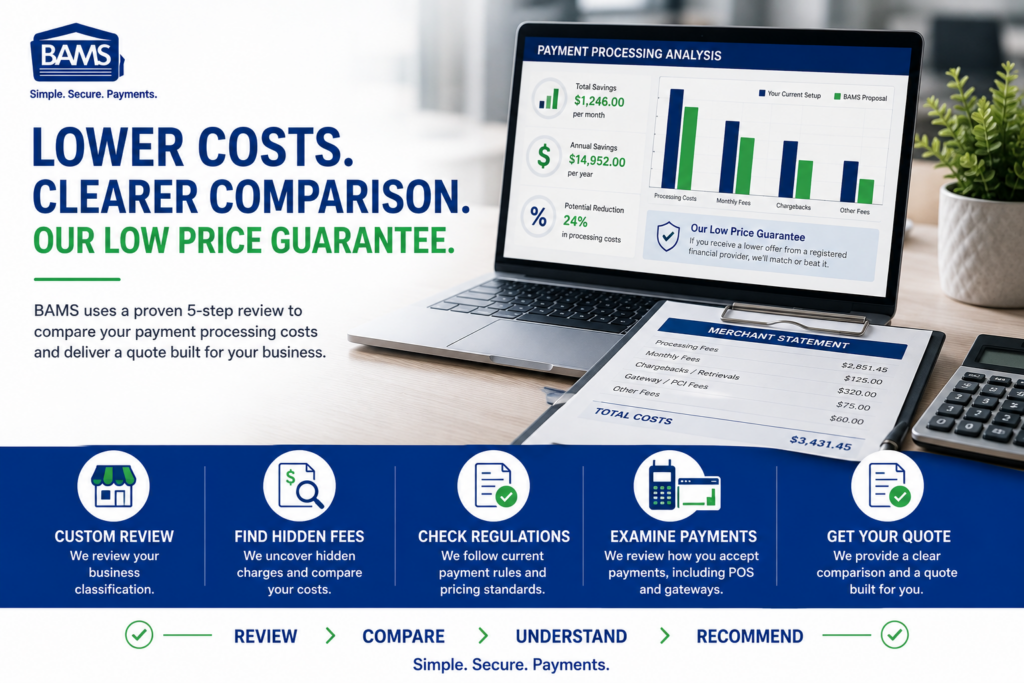
A merchant statement can reveal more than the advertised processing rate. Review markup, fees, transaction categories and funding terms before comparing providers.
You do not need to become an interchange expert before speaking with a processor. A few direct questions can tell you a lot about how transparent the account will be.
- Will my statement show the underlying interchange cost separately from your markup?
- How do you determine which transactions enter each pricing category?
- Are there additional monthly, batch, gateway or account fees?
- Can you compare your pricing against a recent merchant statement?
- What happens to my pricing if my transaction mix or volume changes?
If the answers are difficult to follow, ask for the numbers in writing. A merchant should be able to understand what the processor charges and why.
BAMS also backs its merchant pricing with a Competitive Price Guarantee, giving businesses another way to compare a qualifying merchant account offer against their existing arrangement.
Pricing Matters, but It Is Not the Only Cost
Transaction pricing deserves close attention, but a merchant account affects cash flow in other ways too. Funding speed, chargeback costs, gateway fees and account services can change the overall value of one processing arrangement compared with another.
For businesses where access to cash matters, BAMS also offers guaranteed next day funding for qualifying merchants. It is worth reviewing funding terms alongside transaction rates instead of treating them as separate decisions.
A lower processing rate loses some of its appeal if the rest of the account adds unnecessary cost or friction. Compare the complete arrangement.
BAMS offers interchange-plus pricing to all of our partners, making our merchant accounts and services some of the most affordable in the industry. Combine that guaranteed low-pricing with the wide range of features we offer our merchants, from fraud management to next-day funding and beyond, and it’s clear why so many merchants across the globe prefer BAMS. Request today your unique five-step price comparison and let us show you exactly how much switching to BAMS could save you on your monthly merchant statement.
Frequently Asked Questions
What is the main difference between tiered pricing and interchange-plus pricing?
Tiered pricing groups transactions into processor-defined pricing categories. Interchange-plus pricing separates the underlying interchange cost from the processor’s markup, giving the merchant more visibility into how the transaction cost is built.
Why can tiered pricing be difficult to compare?
The processor determines the rate for each tier and decides how transactions fit into those tiers. A merchant may see the final qualified or non-qualified rate without seeing the underlying interchange cost as clearly.
Does every card transaction have the same interchange rate?
No. Interchange can vary based on factors such as the card, network and transaction characteristics. That variation is one reason merchants should look beyond a single advertised processing rate.
Is interchange-plus always the same price?
No. The underlying interchange cost can change from one transaction to another. The processor’s agreed markup is then added to that cost. The advantage is that the two components can be reviewed separately.
How can I tell which pricing model I currently have?
Start with your merchant statement. Tiered statements often use categories such as qualified, mid-qualified and non-qualified. Interchange-plus statements generally show detailed interchange categories along with a separate processor markup.
Should I compare more than transaction rates?
Yes. Look at the complete merchant account, including monthly fees, gateway costs, funding speed, dispute expenses and other account charges. The lowest advertised transaction rate does not automatically produce the lowest overall processing cost.
How can BAMS compare my current pricing?
BAMS uses a five-step price comparison to review a merchant’s current statement and processing setup. The comparison can help identify how the existing costs compare with a BAMS merchant account.