
The Ideal Merchant Account: Payment Processing with BAMS
Last Updated on October 27, 2026 by Dimitri Akhrin
Your merchant account touches every card sale your business makes. It decides what you pay in fees, how fast you get your money and who picks up the phone when something goes wrong. So choosing the right one has a direct effect on your cash flow and growth.
But what does the ideal merchant account actually look like? Below are six things to look for, plus how BAMS handles each one.
TL;DR
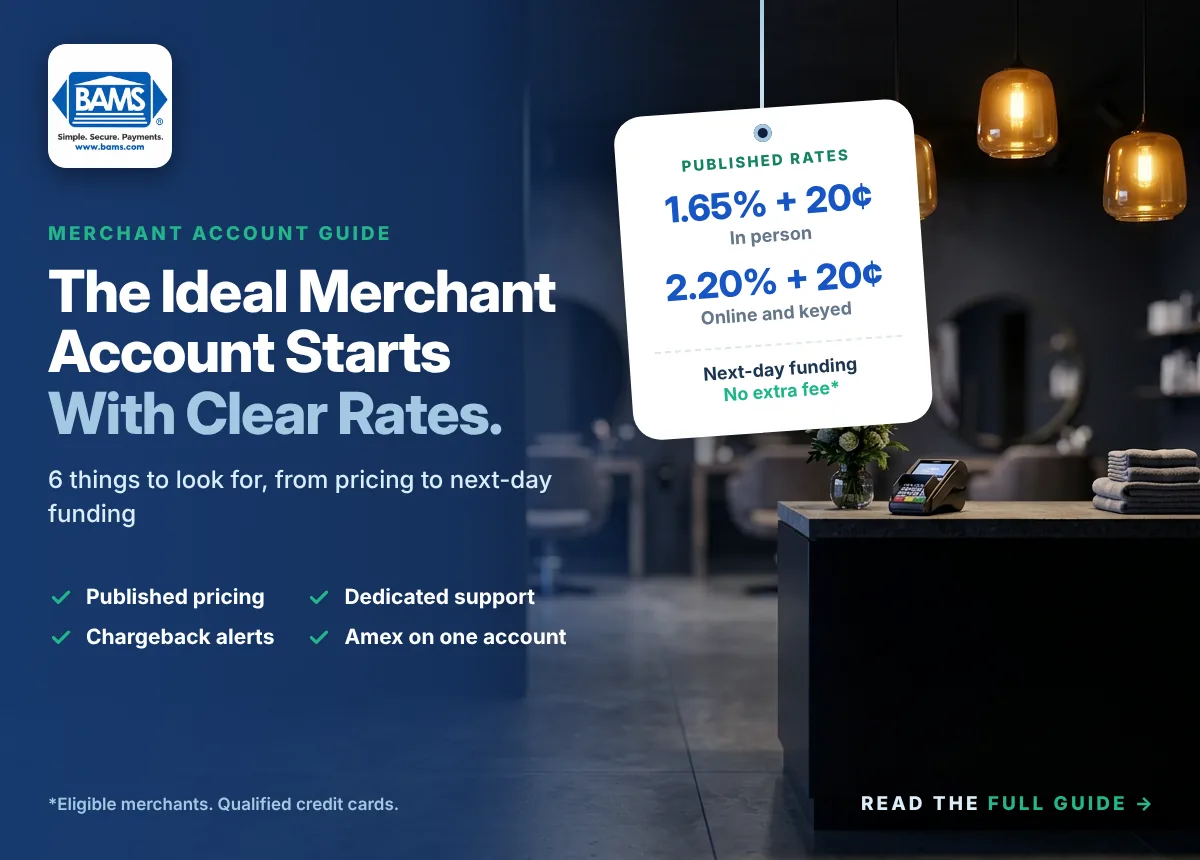
- Clear pricing: BAMS publishes its rates: 1.65% + 20¢ in person and 2.20% + 20¢ online.
- Flexible integrations: Keep the gateway, cart and POS tools you already use.
- Real support: Every merchant gets a dedicated support specialist.
- Chargeback help: Instant dispute alerts and an online evidence checklist.
- Fast funding: Eligible merchants get next-day funding at no extra cost.
- American Express: Accept Amex on the same account through OptBlue.
1. Transparent Merchant Account Pricing
Many processors hide their real costs behind vague tiers and extra fees. Instead, look for a provider that tells you what you’ll pay up front.
BAMS publishes its merchant account pricing. Qualified credit cards cost 1.65% + 20¢ in person and 2.20% + 20¢ for online or keyed payments. Visa, Mastercard, Discover and American Express all cost the same. In addition, businesses with large volumes or unique models can request custom interchange-plus pricing.
Already have a lower offer? With the BAMS Competitive Price Guarantee, BAMS will match or beat a lower fee schedule from a registered provider. Just send the offer on official paperwork.
2. Integrations With the Tools You Already Use
Of course, switching processors shouldn’t mean rebuilding your checkout. The ideal merchant account works with your existing payment gateway, shopping cart and POS system.
BAMS offers its own payment gateway and certified integrations with Authorize.Net, BigCommerce, CyberSource, Magento, Volusion and WooCommerce. As a result, many merchants can keep their current setup and simply move their processing. See the full list of system integrations.
3. Dedicated Customer Support
Whenever a payment problem hits, you need answers fast. Yet many processors route you to a general call center, where you explain your business from scratch every time.
At BAMS, every merchant gets a dedicated support specialist who knows your account. That way, you spend less time on hold and more time running your business. Learn why great customer service matters in merchant services.
4. Built-In Chargeback Defense
Chargebacks cost merchants more every year. In fact, Mastercard expects global chargeback costs for merchants to reach $42 billion by 2028. So your merchant account should help you respond quickly and win more disputes.
BAMS Chargeback Defense sends instant SMS and email alerts when a dispute arrives. Next, it reads the reason code and builds a custom checklist of the documents you need. Then you submit evidence online and track every deadline in one place.
5. Next-Day Funding
Meanwhile, waiting days for your money makes it harder to pay suppliers, staff and bills. Fortunately, faster funding is now within reach for many businesses.
With BAMS next-day funding, eligible merchants who batch before the 9 PM EST cutoff see funds by 7 AM EST the next business morning. BAMS charges no additional fee for next-day funding. It also works with any bank. Note that weekends and holidays follow normal business-day banking.
6. Easy American Express Acceptance
After all, turning away Amex cardholders means turning away sales. However, accepting Amex used to require a separate account and higher costs.
Through the American Express OptBlue program, BAMS turns on Amex alongside your other cards. BAMS then authorizes, settles and reports your Amex sales in the same stream as Visa and Mastercard. Plus, you get one statement and one support contact for every card type. OptBlue fits businesses with under $3 million a year in Amex volume.
How to Choose the Right Merchant Account
Before you sign with any provider, ask these questions:
- Are the rates published, or will I get a written, itemized quote?
- Which monthly, PCI, chargeback and early termination fees apply?
- Will it work with my current gateway, cart and POS?
- Who do I call for help? Will they know my account?
- How fast will funds reach my bank account?
Want to see how your current merchant account compares? Get a BAMS five-point price comparison.
Frequently Asked Questions
What is a merchant account?
A merchant account lets your business accept card payments. It holds funds from card sales before they’re deposited into your business bank account.
How much does a BAMS merchant account cost?
BAMS publishes rates of 1.65% + 20¢ for in-person and 2.20% + 20¢ for online qualified credit card payments. Larger businesses can request custom interchange-plus pricing.
Does BAMS charge extra for next-day funding?
No. BAMS charges no additional fee for next-day funding for eligible merchants.
Can I accept American Express with BAMS?
Yes. Through the OptBlue program, BAMS adds Amex to the same account as your other cards.


