Transaction Authorization Rates: The Risk Signal You’re Ignoring
Last Updated on August 28, 2026 by Dimitri Akhrin
Why your processor is already scoring you — and how authorization and chargeback metrics shape your cash flow
Learn why transaction authorization rates and chargeback ratios are operational signals, not just financial metrics. Discover how processors use these numbers to slow deposits and increase reserves before you even notice.
TL;DR
- Chargebacks cost more than the dispute amount – They degrade your processor’s trust score, leading to higher rolling reserves, slower deposits, and lower authorization rates that compound into serious cash flow disruptions.
- Authorization rates and chargeback ratios are one system – Monitoring them together, weekly, gives you early warning before your processor adjusts your funding terms. Treating them separately means you only find out after the damage is done.
- Payment processing speed is an operational metric – The difference between 86% and 92% authorization isn’t just conversion. It determines whether you can reliably time supplier payments, avoid credit lines, and plan working capital with confidence.
- Predictability is built, not bought – Next-day funding only stays fast when your chargeback ratios and auth rates give your processor no reason to slow it down. Proactive monitoring is the real unlock.
Your Processor Already Knows You’re a Problem
Here’s something most eCommerce managers don’t realize until it’s too late: your payment processor isn’t just moving money. It’s scoring you. Every declined transaction, every chargeback, every ratio that drifts above threshold is a signal. And processors don’t send warnings the way your bank does. They respond by holding your deposits longer, increasing your rolling reserves, or quietly downgrading your transaction authorization rates. By the time you notice the cash flow disruption, the damage has been compounding for weeks.
The “Chargebacks Are a Cost of Doing Business” Myth
For years, the standard advice has been to treat chargebacks as a line item. Budget for them. Factor the loss percentage into your margins. Move on.
This made sense when eCommerce was younger and processors were hungrier for merchant volume. But the payments landscape has become increasingly focused on dispute and fraud management. Mastercard explains that excessive chargebacks can create additional costs for merchants and that effective chargeback management requires understanding why disputes occur and responding with appropriate evidence. Processors also have their own risk-management responsibilities, which means elevated dispute activity can become more than a simple transaction-level loss.
The result? Merchants who treat chargebacks as purely financial events miss the operational cascade they trigger. It’s not just the $50 you lost on a disputed order. It’s the $15,000 in deposits that arrived two days late because your processor adjusted your risk profile.
Chargebacks Don’t Drain Your Revenue. They Drain Your Predictability.
We believe the real cost of chargebacks isn’t the money you lose on disputes. It’s the cash flow predictability you sacrifice when your processor starts treating you like a liability. Authorization rates, chargeback ratios, and funding speed are not three separate metrics. They’re one interconnected system, and merchants who monitor them together build businesses that can plan. Merchants who don’t are constantly reacting.
How Transaction Authorization Rates Become a Cash Flow Problem
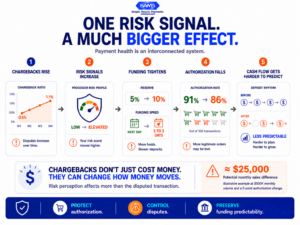
Chargebacks, authorization performance and funding speed should not be viewed in isolation. Together, they can reveal changes in payment health before cash flow becomes unpredictable.
Let’s trace the chain of events that most eCommerce teams never connect.
It starts with chargebacks creeping up. Maybe you launched a new product line with unclear return policies. Maybe friendly fraud ticked upward after a holiday promotion. Whatever the cause, your chargeback ratio climbs from 0.6% to 1.1%.
At 1.1%, you’ve crossed Visa’s threshold. Your processor notices before you do, because they’re the ones who face fines if your ratios stay elevated. Their response is mechanical: they increase your rolling reserve from 5% to 10%, and your funding timeline shifts from next-day to a two or three day hold. Suddenly, the predictable daily deposits you built your cash flow planning around are gone.
But here’s where another payment problem can compound the pressure: declined transactions. Authorization declines prevent otherwise potential sales from becoming completed revenue, while chargebacks can reverse revenue from transactions that were previously approved. Together, they can reduce the amount of payment revenue ultimately available to the business. That’s why authorization performance and chargeback activity are both worth monitoring, even though they occur at different stages of the payment lifecycle.
Now you’re losing revenue on the front end (declined legitimate orders) and losing access to the revenue you do earn (delayed deposits and higher reserves). Your payment processing speed has degraded on both sides of the transaction.
Visa’s research shows 57% of U.S. and U.K. merchants now report authorization approval rates in the 90% range, which means the merchants who aren’t hitting that benchmark are falling behind an improving industry standard. The gap between optimized and unoptimized merchants is widening, and processors notice who’s on which side.
The metrics that actually predict your funding stability
Most eCommerce teams review chargebacks monthly, if that. Authorization rates get checked when someone notices revenue is down. Batch timing is whatever the platform default happens to be. These metrics are treated as separate dashboards, reviewed by separate people, on separate schedules.
The merchants we’ve seen maintain predictable cash flow do something different. They monitor authorization rates and chargeback ratios together, weekly, as leading indicators of processor risk perception. When auth rates dip, they investigate before the processor reacts. When chargeback ratios trend upward, they intervene before crossing thresholds.
This is where merchant services optimization stops being about finding the lowest processing rate and starts being about understanding the operational infrastructure your business runs on. Visa’s payment processing guidance describes authorization as the stage where a transaction is submitted for approval before moving through clearing and settlement. Improving the quality of that payment flow, reviewing decline patterns and maintaining proactive chargeback controls all contribute to a healthier payment operation.
This is also where your choice of merchant services partner matters. BAMS pairs next-day funding with proactive chargeback defense specifically because they understand these metrics are linked. Faster deposits only stay fast when your chargeback ratios and authorization performance give your processor no reason to slow them down.
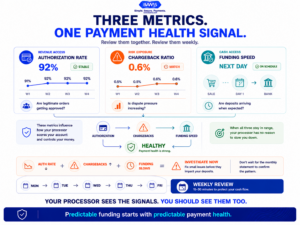
Authorization rates, chargeback ratios and funding speed tell a more useful story when they are reviewed together instead of across separate reports.
What Changes When You Treat These as Operational Metrics
If this framing is right, the implications are significant for how eCommerce teams allocate attention and resources.
It means your chargeback prevention strategy isn’t a customer service function. It’s a treasury function. Every dispute you prevent protects not just the transaction amount, but the funding timeline for every other transaction that month.
It means optimizing batch timing and authorization rates isn’t a payments team project. It’s a working capital project. The difference between 86% and 92% authorization isn’t just conversion. It’s whether you can reliably time supplier payments, take early-payment discounts, or avoid drawing on a credit line.
And it means the merchant who reviews these metrics weekly, together, has a structural advantage over the one who reviews them monthly, separately. Not because they’re smarter, but because they see the signals before the processor acts on them.
A New Way to Think About Payment Health
Stop thinking of chargebacks as losses and authorization rates as conversion metrics. Start thinking of them as your processor’s opinion of you, expressed in how fast and how fully they fund your account.
Your processor doesn’t call you to say “we’re concerned.” They adjust your reserves, they extend your hold times and they tighten your approval parameters. The feedback loop is entirely mechanical, and it’s already running whether you’re watching it or not.
The mental model that works: your chargeback ratio is your processor’s trust score, and your authorization rate is the market’s willingness to let you transact. Manage them together, and you manage the predictability of your entire cash flow.
Predictability Is the Product
Ecommerce businesses don’t fail because a single chargeback wiped them out. They fail because a slow erosion of processor confidence turned predictable next-day funding into unpredictable three-day holds, and nobody noticed until the cash flow gap forced a bad decision. The merchants who win aren’t the ones with the lowest rates. They’re the ones whose deposits arrive exactly when expected, every single time. That predictability isn’t luck. It’s built.
Frequently Asked Questions
How do chargebacks affect payment processing speed beyond the dispute itself?
Elevated chargeback ratios signal risk to your processor, which can respond by increasing rolling reserves and extending deposit hold times. This means even your successfully completed transactions take longer to fund, disrupting cash flow across your entire operation.
What transaction authorization rates should eCommerce merchants target?
Well-optimized eCommerce merchants typically achieve authorization rates between 90% and 95%. If your rates fall below 85%, you’re likely losing significant revenue to false declines and may be triggering negative risk signals with your processor.
Which factors influence the speed of funding in merchant services?
Funding speed depends on your chargeback ratio, authorization performance, batch timing, and your processor’s risk assessment of your account. Merchants with clean metrics and optimized batch schedules are most likely to maintain consistent next-day funding.
Sources
- https://www.visaacceptance.com/content/dam/documents/en/ecommerce-fraud-trends-merchants-adapt.pdf
- https://corporate.visa.com/en/solutions/acceptance/process-payments.htmlhttps://corporate.visa.com/en/solutions/acceptance/process-payments.html
- https://www.mastercard.com/us/en/news-and-trends/Insights/2024/how-can-merchants-dispute-credit-card-chargebacks.html